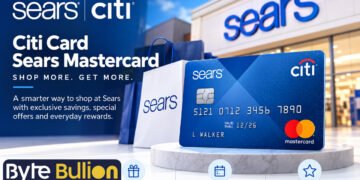


The Citi card Sears Mastercard, also known as the Shop Your Way Mastercard, was a co-branded credit card issued by Citi for shoppers in the Sears and Shop Your Way world. According to NerdWallet, the Citi-issued card launched in 2017 and was discontinued in 2025, and cardholders were moved automatically to the Citi ThankYou Mastercard. If you still have an old Sears Mastercard in a drawer, or you keep seeing the name in search results, this guide explains the background, what changed, how to check your own account, and how to avoid the many low-quality websites that give confusing advice about Sears cards. We use only sources we could read and flag where details are missing.
A Short History of the Card
Sears and Citi worked together on credit cards for many years. A Retail Dive report from May 21, 2018 said that Citi agreed to pay Sears 425 million dollars as part of a deal that extended their partnership for a co-branded Mastercard tied to the Shop Your Way loyalty program. The agreement was pushed out to 2025, and Sears could extend it for another two years. You can read the report in Retail Dive’s article on the Sears and Citi deal.
The report also described Sears in a hard period. Comparable sales fell by more than thirteen percent in 2017, and the deal was one of several moves to raise cash. It said that Citi’s Craig Vallorano noted that seventy percent of customer spending on the card happened at retailers other than Sears, and that the cards carried an interest rate of nearly twenty-seven percent. This is useful background, because it shows that the card was designed as a general-purpose Mastercard that could be used anywhere, not only in Sears stores.
What Happened in 2025
NerdWallet reports that the Shop Your Way Mastercard from Citi was discontinued in 2025, and that cardholders were automatically moved to the Citi ThankYou Mastercard, which earns Citi ThankYou points. The article does not give a month or day, and it does not explain why the card ended. It also says nothing about what happened to balances beyond the move to the new card. You can read the summary in NerdWallet’s article on the discontinued card.
NerdWallet also makes an important point for readers who are confused. The newer Shop Your Way 5321 card is a separate product, issued by First Bank and Trust, and you must apply for it directly, even if you had the older card. So the Citi Sears Mastercard and the 5321 card are not the same thing.
Is Your Old Card Still Active?
We cannot see your account, so the only reliable answer is to check with Citi. If you were moved to a Citi ThankYou Mastercard, you may have received a new card, a letter, or an email. Look at your recent mail and your online statements. Check the name printed on the card, and the issuer name on your statement.
If you are not sure, call the number on the back of the newest card or on a recent statement. Do not use a number from a random website. Ask whether your account was converted, what your current credit limit and interest rate are, and what happened to any rewards points you had.
Rewards: What to Ask About
The old card was known for its rewards in categories such as gas, groceries, and dining, but NerdWallet notes that the point values were low and that statement credit redemption was not allowed on the older Citi card, unlike the newer 5321 card. If you had a balance of Shop Your Way points, ask whether they are still valid, whether they moved to your new account, and how they can be used.
The sources we read do not tell us what happened to unused points. That is why a call to the issuer or a check of your online account is important. Do not assume your points are gone, but do not assume they are safe either. Ask in writing, if possible.
How to Check Your Account Safely
Use the official Citi website or app. Type the address yourself, or use the app from your phone’s official store. Look for the issuer on your statement. If you cannot log in, use the “forgot password” tool on the official page, and have your card number and personal information ready.
Never click on a link in an email or text that claims to be about your Sears card. Scammers often send messages about “card conversion” or “account closing.” If the message asks for your full card number, your PIN, or a one-time code, do not respond. For more advice on staying private online, that guide offers simple habits that help with banking.
The Problem With Low-Quality Guides
When we searched for the Sears Citibank Mastercard, many results were pages with long, generic titles promising a “complete guide” to payments, login, and rewards. Several were hosted on unrelated websites, such as school or business domains, which is a sign of low-quality or spammy content. These pages often copy each other, repeat out-of-date details, and may contain wrong phone numbers or links.
Treat such pages with suspicion. Do not enter your card number or password on any page you reached from a search result unless you are sure it belongs to the issuer. When a guide does not name its sources, move on. A reliable article should say where its facts come from, and should show a date.
What If You Have a Balance?
If you owe money on a Sears or Shop Your Way card, keep paying on time. Late payments can lead to fees and may harm your credit. If your card was converted, make sure your automatic payments still point to the right account. If you pay by mail, use the address printed on your latest statement.
If you are struggling to pay, call the issuer and ask about options. Many lenders have hardship programs, but you usually have to ask before you miss a payment. Write down the date and name of the person you speak to. Having a clear budget can help you decide how much you can pay each month and where to cut costs.
What About Your Credit Score?
Closing or converting a credit card can sometimes affect your credit score, because it can change your total available credit and the age of your accounts. An automatic move to a new card from the same issuer may keep your account history, but we could not confirm the details for this change. Check your credit reports for free from the official sources, and look at how the account appears.
If you see something that looks wrong, such as a closed account that you did not expect or a balance that does not match your statement, contact the issuer and, if needed, file a dispute with the credit reporting company. Keep copies of your letters and emails.
Should You Apply for the 5321 Card?
NerdWallet says the 5321 card is a separate product from First Bank and Trust, and that you must apply for it directly. Whether it is right for you depends on your spending, your credit, and your goals. Compare its rewards, fees, and interest rate with other cards. Do not apply just because you had the older card, and do not apply for many cards at once, since each application can affect your credit.
If you want a general-purpose card, compare several offers. Look at annual fees, rewards that match your spending, and the interest rate if you might carry a balance. Pay in full if you can, which avoids interest on new purchases.
Understanding Co-Branded Cards
A co-branded card carries the name of a store and a bank. The store promotes the card and often offers special rewards, while the bank lends the money and runs the account. Because the bank is the issuer, any change in the partnership can affect the card, as in this case. When a store changes its business or its agreement, the card may be changed or ended.
This is a good reason to read your cardholder agreement, and to keep an eye on notices. Banks must usually give advance notice of major changes to your account, though the exact rules depend on the type of change. Keep letters you receive.
Keeping Your Information Safe
If you receive a new card, activate it only through official channels. Shred old cards and statements you no longer need. Turn on alerts in the issuer’s app so you see every transaction. Use a unique password, and turn on two-step login if offered.
Check your statements each month. If you see a charge you do not recognize, report it right away. And if you stopped using a card, make sure no recurring payments are still attached to it, because failed payments can cause problems.
When the Store Is Gone
Many people remember Sears as a major retailer, and the company has changed a lot over the years. Even if a store has closed in your area, a credit card issued by a bank remains a legal agreement between you and the issuer until the account is closed and paid off. The store’s situation does not erase your balance.
If you are unsure who to pay, look at your statement. It names the bank and gives instructions. If the statement is missing, request a copy from the issuer.
Conclusion
The Citi-issued Sears and Shop Your Way Mastercard began in 2017, was part of a long partnership that Citi and Sears extended in a 2018 deal worth 425 million dollars, and was discontinued in 2025, according to the sources we could read. NerdWallet reports that cardholders were automatically moved to the Citi ThankYou Mastercard. The newer Shop Your Way 5321 card is a different product from another issuer. Because we could not find official details on balances and points, the safest path is to check your statements and contact Citi using a number from your newest card.
Keep paying on time, protect your login details, and avoid unreliable guides. A few careful steps will keep your account and your credit in good shape.
Frequently Asked Questions
1. What happened to the Citi Sears Mastercard?
NerdWallet reports that the Citi-issued Shop Your Way Mastercard was discontinued in 2025 and cardholders were moved to the Citi ThankYou Mastercard.
2. Is the Shop Your Way 5321 card the same card?
No. It is a separate product issued by First Bank and Trust, and you must apply for it directly.
3. What happened to my points?
The sources we read do not say. Ask Citi to confirm the status of your rewards in writing.
4. Do I still owe money on my old card?
Yes, if you had a balance. Check your latest statement and keep paying on time.
5. How do I avoid fake help pages?
Use the official Citi site or app, type the address yourself, and ignore messages that ask for your PIN or one-time codes.