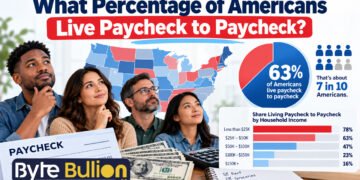


What percentage of Americans live paycheck to paycheck? Many recent surveys say between 56% and 67%, which means about six in ten adults feel they spend nearly everything they earn. Bank of America’s spending data gives a much lower number, about 24% of households, because it counts only homes that spend almost all of their income on basic needs. Both numbers are real, and each one shows a different side of the story. In this guide, you will see the latest figures from LendingClub, PYMNTS, Bankrate, the Federal Reserve, and Bank of America. You will also learn why the numbers do not match, who feels the most pressure, and how to build a small safety cushion.
How Many Americans Live Paycheck to Paycheck in 2026?
About six in ten Americans say they live paycheck to paycheck, but the exact number changes from one survey to the next. LendingClub asked more than 3,000 U.S. consumers whether they need their next paycheck to cover their monthly spending, and 62% said yes. PYMNTS Intelligence reported a higher figure of about 67% for 2025, and the share rose above 70% in some months of that year. A Leger poll from May 2025 found that 56% of Americans live this way. Bankrate reported a lower share of 34%.
Bank of America Institute gives the lowest number. Its 2025 estimate says nearly 24% of U.S. households live paycheck to paycheck. The newest reports available in October 2026 mostly describe 2025 and early 2026, so treat every figure as a snapshot, not a final count. The next sections explain why these numbers sit so far apart and what each one really tells you.
What Does Living Paycheck to Paycheck Mean?
Living paycheck to paycheck means you spend almost all of each paycheck before the next one arrives, so you have little or nothing left to save. Most people use the phrase in a personal way. If your money runs out a day or two before payday, you probably feel you live this way, even if your income is fair and you pay every bill on time.
Researchers use stricter rules. Bank of America Institute counts a household as paycheck to paycheck when it spends more than 95% of its income on necessities such as housing, gas, groceries, utilities, and internet service. This method looks at real spending, not feelings. A household that spends a lot on trips or dining out does not fit that rule, even if it saves nothing at the end of the month.
Money pressure also grows when the cost of living rises faster than pay. Rent, food, and insurance get more expensive, and a paycheck that once left $200 extra may now leave nothing. That is why the share of people who feel stuck changes from year to year, even when pay stays steady.
Why Do Surveys Show Different Numbers?
Surveys show different numbers because each one asks a different question and counts a different group of people. Some ask how you feel about your money. Others measure what you actually spend. The table below puts the main sources side by side.
| Source | What it measures | Share | Report date |
|---|---|---|---|
| LendingClub and PYMNTS | Adults who need their next paycheck to cover monthly spending | About 62% | 2025 and 2026 |
| PYMNTS Intelligence | Consumers who say they live paycheck to paycheck | About 67% | 2025 |
| Leger poll | Adults who say they live paycheck to paycheck | 56% | May 2025 |
| Bankrate | Adults who say they live paycheck to paycheck | 34% | Published 2025 |
| Bank of America Institute | Households that spend more than 95% of income on necessities | About 24% | 2025 |
The gap between feelings and spending is large. EconoFact, a research-based fact-check site, pointed out that almost half of Americans in a Bank of America survey said they lived paycheck to paycheck, yet only about a quarter spent 95% of their income on necessities. In other words, many people feel squeezed even when their basic costs do not take every dollar.
Neither number is wrong. The high numbers show how many people feel money stress. The lower number shows how many households have almost no choice in how they spend. Together, they give you a fuller picture than any single figure can.
What Does Bank of America Data Say?
Bank of America Institute estimates that nearly 24% of U.S. households lived paycheck to paycheck in 2025, up slightly from 23.7% in 2024. The institute bases its work on how its customers spend money, so the results show real behavior instead of opinions. The growth also slowed. The increase in 2025 was about three times smaller than the year before.
The story looks different by income level. Among lower-income households, 29% lived paycheck to paycheck in 2025, compared with 28.6% in 2024 and 27.1% in 2023. Middle-income and higher-income households barely changed. The institute said that lower-income Millennials and Gen X households drove most of the rise. It also found that higher-income Millennials saw their pay grow about five percentage points faster than lower-income Millennials, which helps explain the split.
The institute also warned that rising costs could bring new pressure to regions that improved in 2025, mainly parts of the South and West. If you want the full details, you can read the Bank of America Institute report on its website.
Who Lives Paycheck to Paycheck the Most?
Younger adults, lower-income households, and people in high-cost areas feel the most pressure. The Leger poll found that 62% of adults aged 18 to 34 and 61% of adults aged 35 to 54 said they live paycheck to paycheck. Among adults 55 and older, 46% said yes and 48% said no. Money stress also crossed party lines in that poll, with 56% of independents, 54% of Democrats, and 53% of Republicans reporting the same struggle.
Bank of America’s spending data adds a different angle. In its 2024 analysis, the institute found that about 35% of households earning under $50,000 lived paycheck to paycheck, up from 32% five years earlier. It also found that nearly 30% of baby boomer households fit the rule. Polls show younger adults feel more strain, while spending data shows older households also spend most of their income on needs such as housing and health costs.
Location matters too. The South Atlantic region, which includes North Carolina, had the highest share at about 28%. The Northeast Mid-Atlantic had the lowest. Housing costs, family size, and local prices all play a part, and many of these costs are hard to cut without a big change, such as moving.
Do High Earners Live Paycheck to Paycheck Too?
Yes, many people with high incomes also report living paycheck to paycheck. PYMNTS Intelligence found that about half of consumers earning $100,000 or more said they lived paycheck to paycheck in January 2025. That result surprises many readers, because most people link this problem with low pay.
Bank of America’s data supports the idea, though with a smaller number. In its 2024 analysis, about 20% of households earning more than $150,000 a year appeared to save very little. The institute said the share of paycheck-to-paycheck households falls only slowly as income rises. Large fixed costs, such as mortgages, property taxes, car loans, and child care, take a big bite out of a high salary.
Choices play a role as well. Some high earners buy bigger homes or carry more debt as their pay grows, and their spending rises to match. A bigger paycheck helps, but it does not fix the problem unless spending stays in check.
Why Do So Many Americans Have No Money Left Over?
Higher prices for housing, food, insurance, and daily needs leave less money after each paycheck. In Bankrate’s 2026 emergency savings report, 54% of Americans said inflation made them save less. Bank of America also noted that inflation ran ahead of after-tax pay for many middle-income and lower-income households through much of 2025. When prices rise faster than pay, the extra money at the end of the month shrinks first.
Job changes and surprise bills add to the problem. In the same Bankrate report, 26% of people who saved less pointed to a change in income or a job loss. PYMNTS Intelligence reported that nearly three in four people who now live paycheck to paycheck did not start there. Many slid into it after a setback, such as a bill they could not predict or a drop in hours at work.
Many necessary costs are also hard to cut. Rent, car payments, and health care do not shrink on request. If you like clear explanations of money, law, and daily topics, the guide to everyday money and law explainers on Fento Magazine shows one place to keep learning. Reading widely helps you spot the costs that quietly drain your budget.
How Much Savings Do Americans Have?
Many Americans have a thin savings cushion, and the numbers show a clear gap between those who can handle a surprise bill and those who cannot. Bankrate’s 2026 report found that 53% of Americans could not pay a $1,000 emergency from savings, and 24% had no emergency savings at all. About 37% had dipped into their savings during the past year.
Other surveys paint a slightly brighter picture. EconoFact reported that the Federal Reserve found 54% of Americans have emergency savings that could cover three months of expenses. The difference comes from the wording of the questions and the groups surveyed. One survey asks about a $1,000 bill, while another asks about three months of costs.
Small savings matter because they break the cycle. Without a cushion, a flat tire or a medical bill goes on a credit card, and the debt then takes a share of future paychecks. If you want more everyday finance reading, Plusstories.com is a general-interest site that covers business and finance topics, and Fento Magazine explains what it offers.
Is Living Paycheck to Paycheck the Same as Being Poor?
No, living paycheck to paycheck does not always mean poverty. Many households live this way while paying every bill on time. They simply have little or no money left each month. The EconoFact example shows this clearly, since almost half of people in one survey said they lived paycheck to paycheck while only about a quarter spent nearly all of their income on necessities.
Real hardship is still common, though. Jeffrey Fuhrer, an economist cited by EconoFact, estimated that about 43% of U.S. families fall short of meeting basic needs when you look beyond the official poverty rate. So the problem is real for many people, even when the label does not fit everyone the same way.
The difference matters for your plan. If your bills are covered but nothing remains, you may improve your situation by tracking spending and trimming a few costs. If your bills already exceed your income, you may need a bigger change, such as higher pay, a lower rent, or help from a nonprofit credit counselor.
How Can You Stop Living Paycheck to Paycheck?
Start small by tracking your spending for 30 days and saving a tiny amount from every paycheck. Write down every purchase, or use your bank app to sort them into groups. Most people find a few costs they forgot, such as unused subscriptions or small daily buys that add up to real money.
Next, set up an automatic transfer on payday. Even $25 per paycheck builds a cushion over time, and automatic saving works because you never see the money. Aim first for a starter fund of $500 to $1,000, then grow it toward three months of basic costs. Keep that money in a separate savings account so you do not spend it by mistake.
After that, look at your biggest bills. Housing, transport, and debt usually take the largest share, so small changes there save the most. You can call your insurance company to compare rates, ask your lender about a lower interest rate, or pay off high-interest card debt first. Each dollar you stop paying in interest becomes a dollar you can save.
Finally, think about income. A side job, extra hours, or a raise request can add room to your budget. When your pay goes up, save part of the increase before your spending rises to match it. This article gives general information, not personal financial advice, so talk with a licensed professional if you face a complex money problem.
Conclusion
So, what percentage of Americans live paycheck to paycheck in 2026? The honest answer is a range. Most self-reported surveys land between 56% and 67%, while Bank of America’s spending data shows about 24% of households with almost no room in their budgets. The pressure is strongest for lower-income households, younger adults, and people in costly areas, but high earners feel it too. You cannot control prices, but you can track your spending, save a small amount each payday, and build a cushion one step at a time.
Frequently Asked Questions
What percentage of Americans live paycheck to paycheck?
Most surveys say between 56% and 67% of Americans live paycheck to paycheck. LendingClub found 62%, PYMNTS Intelligence reported about 67% for 2025, and a Leger poll found 56%. Bank of America Institute estimates a lower figure, nearly 24% of households, because it counts only high spending on necessities.
Why is Bank of America’s number so much lower than other surveys?
Bank of America looks at real spending, not opinions. It counts a household only when it spends more than 95% of its income on necessities. Other surveys ask people how they feel, so many adults who have a little room left still say they live paycheck to paycheck.
Do people with high incomes live paycheck to paycheck?
Yes, many do. PYMNTS Intelligence found that about half of consumers earning $100,000 or more said they lived paycheck to paycheck in January 2025. Bank of America found that about 20% of households earning over $150,000 save very little, often because of large housing, tax, and debt costs.
Which age group struggles the most with paycheck to paycheck living?
It depends on the measure. A May 2025 Leger poll found that 62% of adults aged 18 to 34 and 61% of those aged 35 to 54 live paycheck to paycheck. Bank of America’s spending data shows rising pressure among lower-income Millennials and Gen X households, and nearly 30% of baby boomer households.
How much emergency savings should I aim for?
Start with a small goal of $500 to $1,000, then build toward three months of basic costs. Bankrate found that 53% of Americans could not cover a $1,000 emergency from savings in 2026. Even $25 per paycheck helps you move toward the goal. Talk with a licensed professional for personal advice